All Categories
Featured
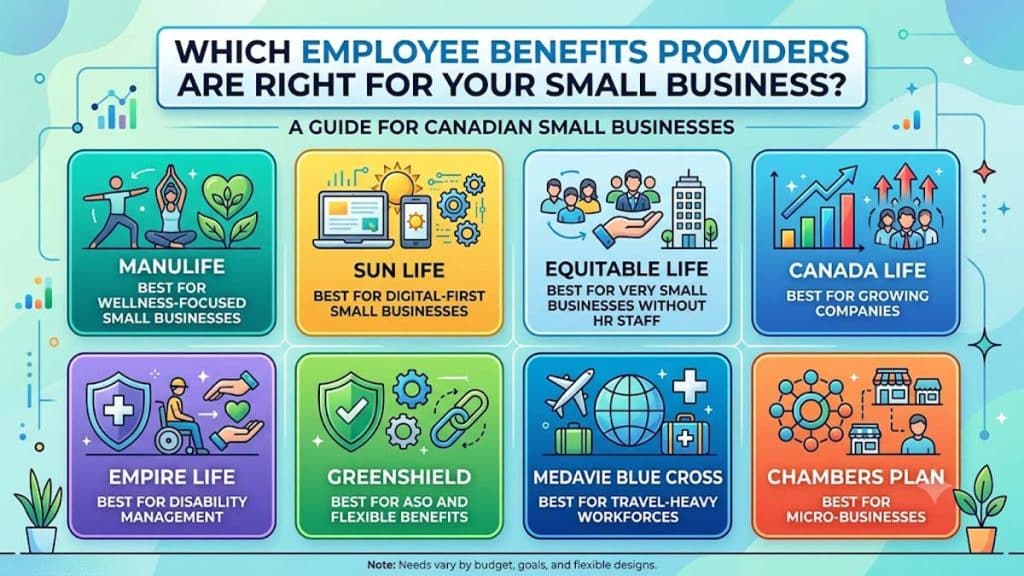

Reviewing Commercial Insurance Options for Small Teams
Table of Contents
Keep your group delighted, healthy, and engaged. We'll guide you to the best medical insurance strategy while browsing compliance and staying within your budget. Enlist your employees seamlesslyChoose from several top-tier strategy providersIntegrate easily with your payroll.
Do you know how to pick health insurance prepares for your organization? Sure, you might provide conventional group medical insurance to your workers, but that's not your only option. There are several small company medical insurance options you can pick from. Why not pick the program that fits your organization? Continue reading to discover about small company health care choices to help you pick one that keeps your employees (and spending plan) pleased.
QSEHRA: small companies under 50 repay workers for individual premiums and medical expenses; tax-deductible for companies. ICHRA: any company can reimburse employees for private plan expenses, need to correspond within worker classes and is tax-free. Excepted advantage HRA: supplemental compensations for dental, vision, copays; must accompany a traditional group strategy.
Business Insurance OceansideNot all workers have the choice to register. And those who do have access to benefits don't constantly benefit from them. According to the Bureau of Labor Data, 72% of private market workers have access to medical care benefits. And, 45% take part in them. Offering competitive advantages while also keeping your company costs low is hard for lots of small businesses.
Analyzing Workplace Wellness Program Costs
Just how much does health insurance coverage cost employers? Employers pay roughly for single coverage and yearly for an employee with household protection insurance. Thankfully, small company owners have some program alternatives and tax incentives that aren't offered to bigger employers (e.g., employers with 50 or more workers). Take a look at some of the medical insurance options for small service owners listed below.
Traditional group health insurance is where an employer picks a strategy, or plans, to use workers. Generally, the company foots part of the expense, and the employee pays the other part. how much does health insurance coverage expense? With a traditional group health insurance plan, companies and employees pay regular monthly premiums.
The staff member is likewise responsible for copays and deductibles related to the strategy they pick. Have a look at some realities about standard group medical insurance plans: Companies pick strategies to provide employees Staff members contribute pre-tax premiums toward their strategy Companies generally contribute an excellent part of the premium cost Streamline Health Advantages Administration Our totally free combination with SimplyInsured lets you look for health insurance strategies, compare expenses, just management, and instantly sync advantages reductions with Patriot's payroll software.
Professional Tips for Small Business Insurance Selection
QSEHRAs are conventional group health plan alternatives that let employers reimburse employees for individually-obtained premiums and qualified medical costs. Usually, HRAs compensate staff members for specific medical expenditures, such as medication or crutches. A QSEHRA is a standalone HRA that compensates staff members for premiums, too.
Business Insurance OceansideUnlike traditional health insurance plans, companies with an ICHRA do not directly supply strategies to employees. Instead, workers pick their own health insurance plan, and employers compensate them for the cost of part or all of their plan.
Employers can not provide both to an employee ICHRAs are tax-free Employers with 50 or more employees have more stringent policies for ICHRA repayments An excepted benefit HRA is a supplemental insurance alternative that began in January 2020. Employers can only use an excepted benefit HRA if they also provide a standard medical insurance strategy.
Steps to Audit Your Assistance Programs
How do these plans work? Through an excepted benefit HRA, companies compensate employees for qualified expenses. Have a look at some of these facts about excepted benefit HRAs: The yearly contribution limitation is $2,200 for 2026 It should be provided in combination with a conventional group health insurance strategy Excepted advantage HRAs do not spend for main health insurance coverage premiums There are a variety of distinctions in between the small company health insurance alternatives out there.

Table of Contents
Latest Posts

Selecting Small Business Health Plan Packages
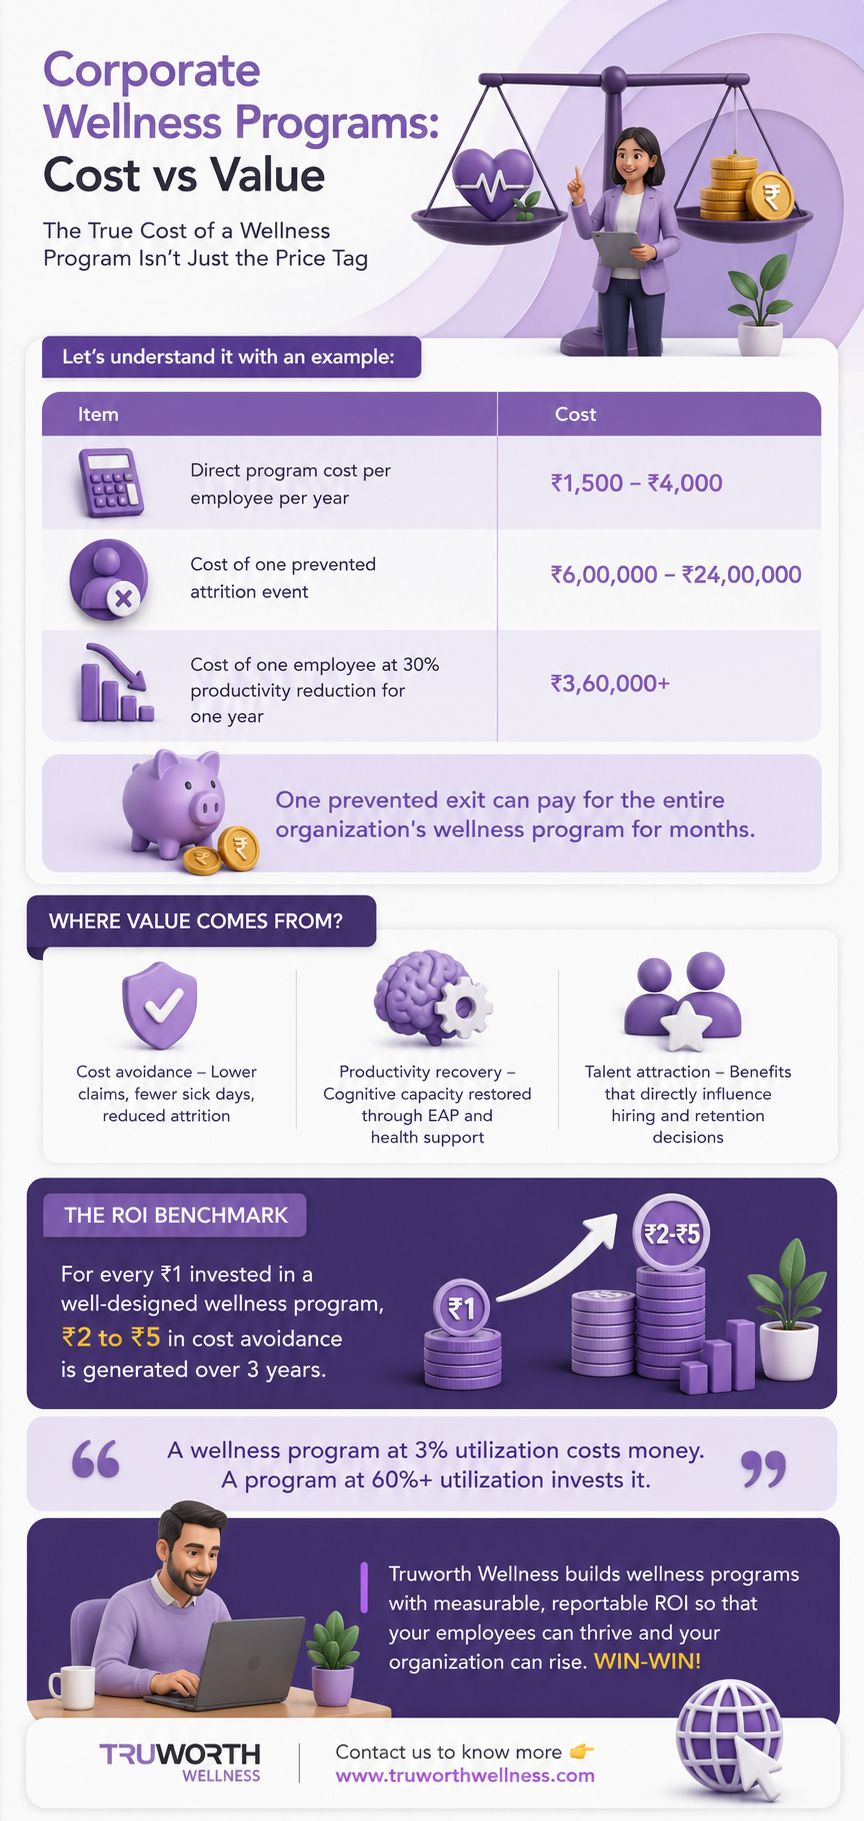
Reviewing Payroll Protection Programs for Modern Growing Businesses

How EAPs Influence Business Commitment in Rancho Cucamonga Firms
Latest Posts
Selecting Small Business Health Plan Packages
Reviewing Payroll Protection Programs for Modern Growing Businesses
How EAPs Influence Business Commitment in Rancho Cucamonga Firms